France's public debt is set to continue soaring. It is expected to climb from 119.3% of gross domestic product (GDP) in 2026 to 121.7% in 2027, according to figures from the government's draft budget bill that the Finance Ministry released on Saturday, September 19. That would represent a new record. In 2010, the public debt stood at 86% of GDP. Experts expect it to keep rising through the end of the next five-year presidential term. "As long as the public deficit stays above the 3% of GDP benchmark, the debt will increase; it's a mechanical effect," said a source at the Finance Ministry.
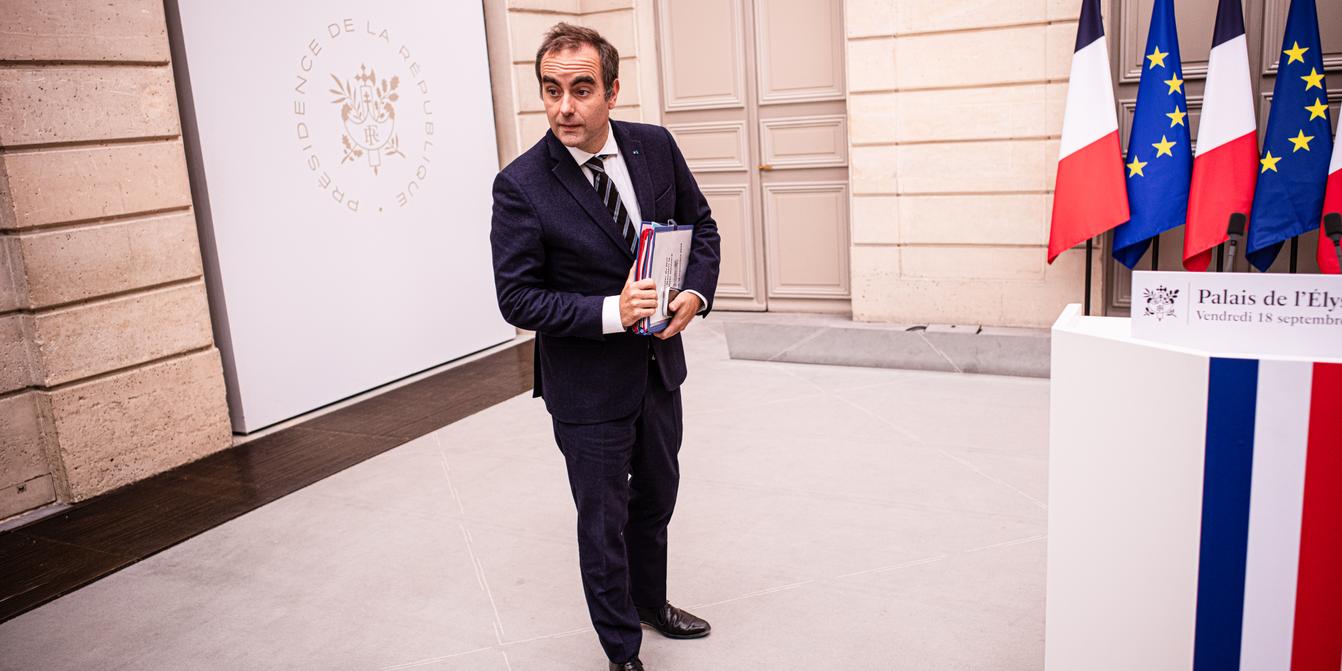
The other major element of the draft budget bill, which was submitted to the High Council of Public Finances on Friday, September 18, concerns mandatory levies. For 2027, Prime Minister Sébastien Lecornu has pledged "tax stability" – a phrase that has become his budgetary mantra – and even a slight reduction in taxes for large corporations. However, the figures included in the bill tell a very different story. If this budget were adopted, taxes and other mandatory levies would, in fact, continue to rise. This increase will be the main factor in restoring public finances as hoped for, as they are currently off track.
General
French public debt to reach new record level in 2027, exceeding 120% of GDP
Source
Le Monde
· Denis Cosnard